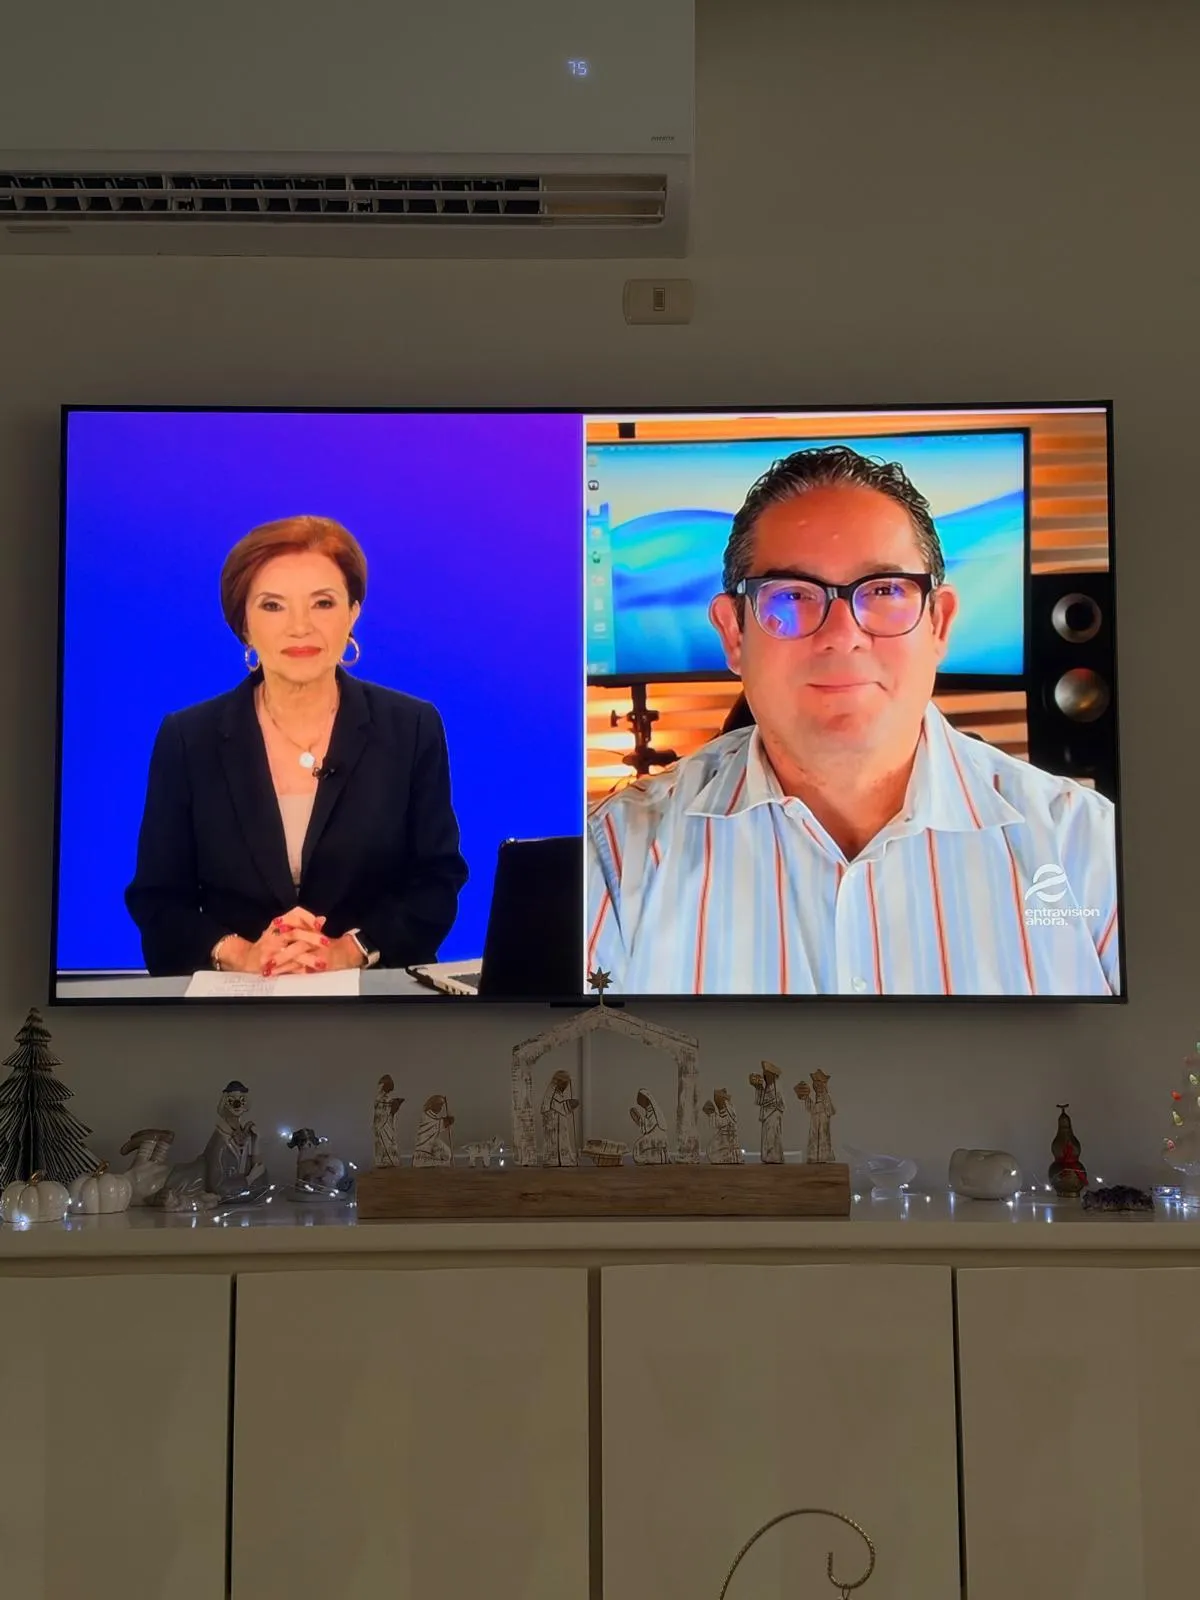
This afternoon I was back on television for the same banking outage, this time on Entravision’s En Foco, live by Zoom with Lourdes Del Río.
A day earlier I had been on Noticiero Univision telling people their money hadn’t gone anywhere. Today the question was the next one: if Chase has a software glitch, why do Bank of America and Wells Fargo customers feel it too — and how worried should you actually be?
The systems wait on each other
Banks are not islands. Their systems, as I put it on the air, “dependen unos de los otros” — they depend on one another. For a transaction to go through, whether it’s a message, a transfer or a wire, somebody has to send it and somebody has to confirm they received it.
When one of those pieces fails, the others don’t shrug and move on. They wait. They sit there expecting a confirmation that isn’t coming. And this is happening at an enormous volume of transactions, which is how a problem in one place turns into a pileup everywhere else. That’s the chain I described:
“puedes crear una cadena de domino donde empiezan a fallar todos los otros sistemas esperando las respuestas”
“you can create a chain of dominos where all the other systems start failing while waiting for the responses.”[1]
Chase has said this was a software failure in its own systems, and that there was no evidence it was cyber-related. Other banks still felt it, because a lot of transactions had Chase on one end of them. By early Tuesday, outage reports were back to normal.[2][3]
A software bug at the largest bank in the country can look, from your phone, like the whole system is coming apart. That is connected plumbing behaving like connected plumbing. It is not, by itself, a disappearing balance.
Can we rule out a cyberattack?
Lourdes asked the question a lot of people were asking after a rough week of outages: what lets anyone say, with confidence, that this wasn’t a cyberattack?
My answer was not a yes. I don’t think there’s enough information at this moment to rule it out. That is not the same thing as saying it was one. Chase has attributed it to a software failure, and there is still no confirmed evidence of a cyberattack. “No confirmed evidence” is also not the same as closing the book from a Zoom window.[1][2]
The bigger point I wanted to make is about the risk landscape we’re already in. Attackers are using artificial intelligence to get into systems in ways we haven’t had to deal with before, and that opens a range of problems we still don’t fully understand. Some of the systems people rely on are old, they’re being overloaded by the volume of data these tools generate, and they can fail under that load — on top of whatever vulnerabilities are already sitting there.
I also said that when a serious vulnerability shows up, the systems often can’t be patched in a matter of hours, while attackers using AI may be able to exploit them in minutes. And there are now autonomous AI systems that could be attacking in ways we can’t yet identify. None of that is a diagnosis of what happened at Chase on Monday. It’s why I won’t pretend we can rule things out before there’s a real investigation.
Are the banking apps we use every day vulnerable?
Banking apps, when it comes to security, are among the systems that get locked down the most. That is not the same as invulnerable.
What’s changed is the new generation of attacks. They can spot weaknesses that traditional security tools have missed, and some of the newer penetration-testing tools are being automated and used by attackers too. Traditional security is dealing with a new class of potential attacks, and that’s the gap I was talking about.
What you should actually do
The part that matters at home is more boring, and more useful.
A lot of our personal information is already out on the internet. I told viewers they can go to a site like Have I Been Pwned, enter their email, and see whether their data has already been exposed — sometimes a long time ago, even if nobody has used it against them yet. Social Security numbers and other records have leaked in old breaches. You have to operate as if that information is already out there.
That means putting a lock on everything that still matters: two-factor authentication, and passwords that can’t be easily guessed. And don’t use your phone number as that second factor. SIM swapping is real — someone gets your number moved to another phone, then intercepts the text message that was supposed to protect your bank account.
What I recommended on the air is an authenticator app:
“lo que se recomienda es un autenticador que puedes utilizar uno gratis Google tiene unos, Microsoft tiene otro que que generan unas cifras cada minuto que son criptologicamente fuertes”
“what’s recommended is an authenticator — you can use a free one. Google has one, Microsoft has another — that generate numbers every minute that are cryptographically strong.”[1]
Those codes don’t travel over a channel you don’t control. Use them on your bank, your personal accounts, the household logins, work, school — anything you’d hate to lose. Google Authenticator and Microsoft Authenticator are both free.
Where this lands
I wasn’t there to panic anybody, and I wasn’t there to tell anybody the case is closed. One bank’s software glitch can knock over a lot of other tiles because the tiles are standing on the same table. Your money didn’t vanish when the app wouldn’t open. And the most useful thing you can do before the next outage is get off SMS codes and onto an authenticator.
If you missed yesterday’s segment, the Noticiero Univision recap is here.
References
- Otter.ai transcript of the Entravision Zoom interview on En Foco with Lourdes Del Río, November 17, 2026, 12:30 p.m. ET. Spanish quotes are taken verbatim from that transcript, which has speech-recognition errors; only the clearest stretches are quoted. English translations are mine. No official Entravision clip or page had been published at the time this was written.
- "'Software bug' in JPMorgan Chase systems halts online banking" (November 16, 2026). POLITICO. Chase said it had "experienced a temporary issue related to a software bug in on-premise hardware systems," that there was no evidence it was cyber-related, and that customers still had access to their accounts and funds.
- "Widespread service outages at major U.S. banks appear to be over" (November 17, 2026). CBS News.